


The Interest Rate In Canada Just Went Up Again & Here's What It Actually Means For Your Wallet
According to an expert, that stress test might get a bit more stressful.
The Bank of Canada (BoC) has once again increased the policy interest rate, bringing it to a new high for the year.
On September 7, the Bank of Canada announced that it is raising the policy interest rate by .75%, bringing it to a whopping 3.25%.
This is the fifth consecutive interest rate hike this year, and BoC's statement seemed to hint at more increases coming up in the future.
The financial regulator also stated that this increase in policy interest rate is to combat inflation in Canada.
If all of this is making you worry about affordability in your life, Narcity spoke with a financial expert to understand how this will affect Canadians and what can be done to avoid the brunt of it.
According to Leah Zlatkin, a licensed mortgage broker and an expert from LowestRates.ca, one of the groups most affected by this increase is Canadians who have taken out a variable rate mortgage.
These are mortgage rates that change based on the policy interest rate and the condition of the Canadian economy.
This means that for every $100,000 in a mortgage, homeowners will see an approximate increase of $36 a month. That can really start to add up!
The other group that will be feeling this increase the most is any Canadian hoping to qualify or re-qualify for a mortgage.
"Typically, rates are floating around 3.7% on a variable but a .75% increase means they will need to qualify at 4.45%," explained Zlatkin.
"This is before even taking into account the stress test which is an additional 2%, meaning they are looking at 6.45% in order to qualify."
However, all hope is not lost. Zlatkin provided some tips that could help save cash during moments like this.
Her first tip is to pay as much of a lump sum off your mortgage as possible.
"This allows [you] to pay less interest long-term with more principal down," she said.
However, it's less common to have a lump sum of money you can throw down at a moment's notice, so she offers some additional advice.
"It's a good idea to set aside more cash for future payments to ride out the storm," said Zlatkin, "[you] should also consider speaking with a professional to see about options for changing products or switching amortization periods."
But, she mentions that before you make any moves, you should consult the terms and conditions of your mortgage to "understand what the penalties might be."
While the inflation rate has gone down from 8.1% in June to 7.6% in July, it still is far off from the Bank Of Canada's goal of 2%.
Experts believe that the Bank of Canada may increase prices again later this year, with the next hike expected on October 26.
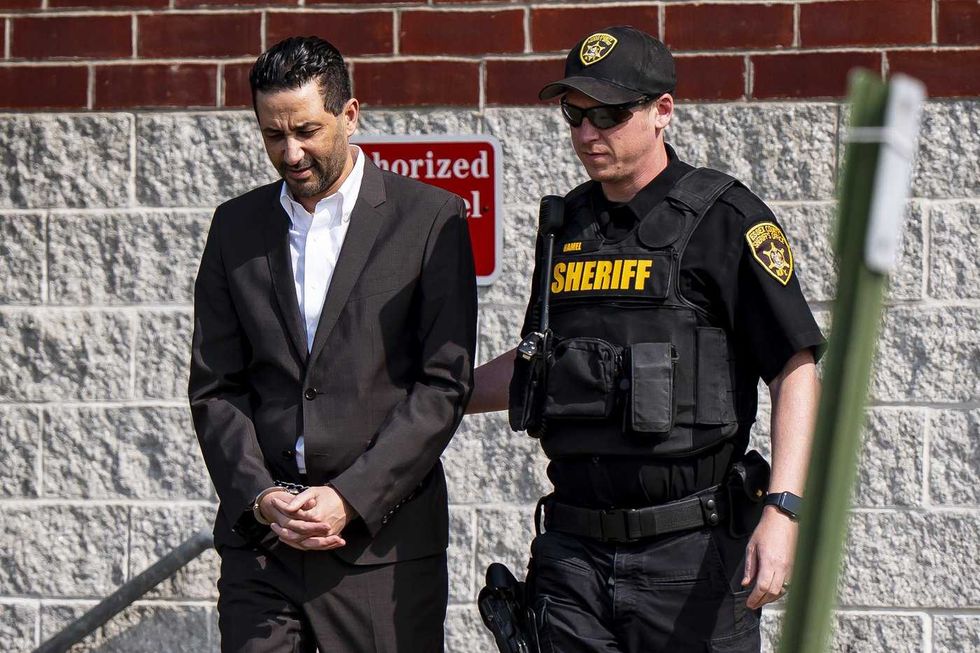 Luciano Frattolin is taken away in custody from the Essex County Court in Elizabethtown, New York on Friday, July 24, 2026. Luciano Frattolin charged with 2nd-degree murder and concealment of a human corpse.
THE CANADIAN PRESS/Christopher Katsarov
 Police officers open the back of a recovered truck during a press conference regarding Project 24K, a joint investigation into the theft of gold from Pearson International Airport, in Brampton, Ont., on Wednesday, April 17, 2024.
THE CANADIAN PRESS/Arlyn McAdorey
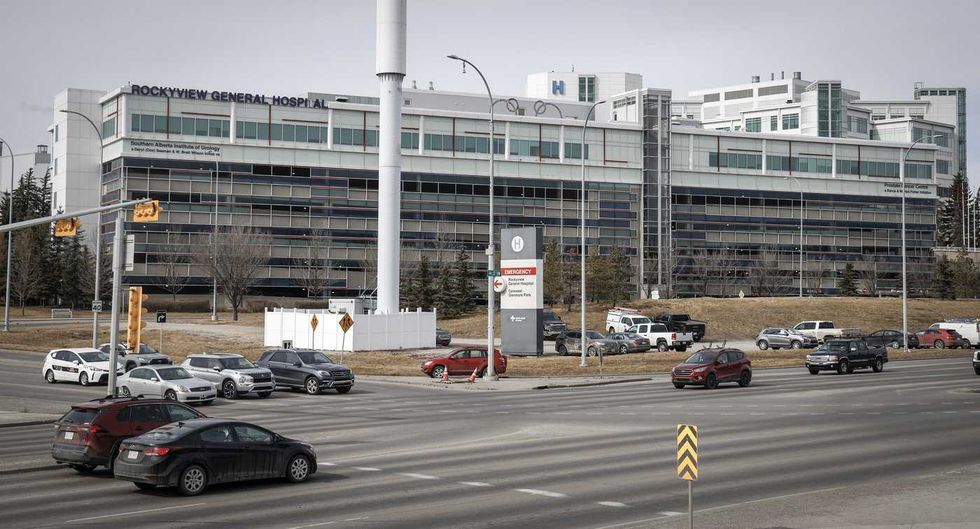 The Rockyview General Hospital is pictured in Calgary, Thursday, March 20, 2025.
THE CANADIAN PRESS/Jeff McIntosh
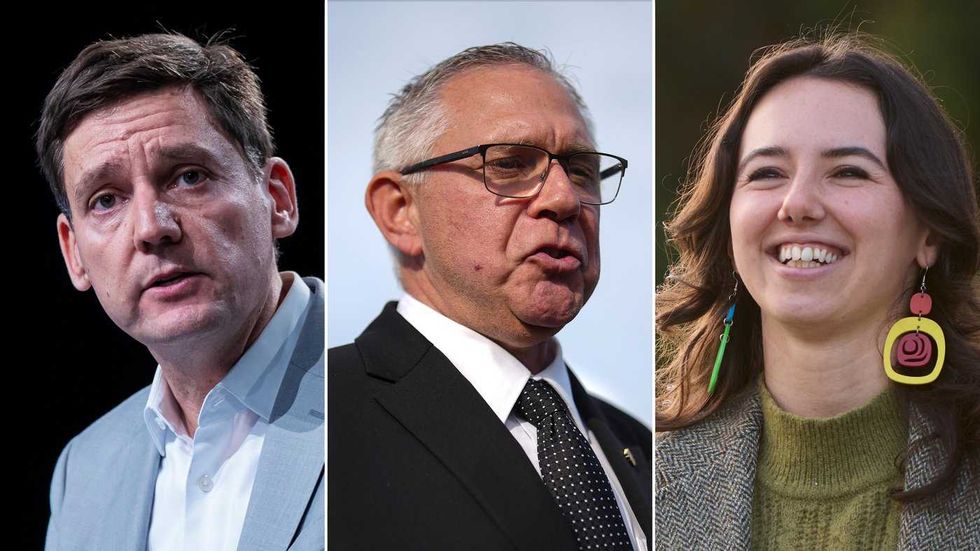 This composite image shows, left to right, B.C. NDP Leader David Eby in Vancouver, on April 13, 2026; B.C. Conservative interim Leader Lorne Doerkson, in Vancouver, on Sept. 22, 2026; B.C. Green Party Leader Emily Lowan in Victoria, on Sept. 23, 2026.
THE CANADIAN PRESS/Darryl Dyck, Rich Lam, Kevin Light